What Is an Adverse Action Notice? A Guide for Lenders
Introduction
A borrower submits a loan application, and the lender reviews the application details before assessing the associated risks. After careful evaluation, the lender may still decide not to extend credit. However, declining an application rarely marks the end of the lender's responsibilities.
At the same time, U.S. lending laws are different. That means much of the responsibility lies on lenders' shoulders. Creditors must explain certain credit decisions and meet applicable notification requirements. The reasons must be specific. Accurate. And tied to the actual decision. As lenders process more applications through automated underwriting systems, keeping these explanations consistent becomes another operational challenge.
That is where adverse action notices come in. They give applicants a formal explanation of adverse credit decisions. That, as a result, helps lenders meet their regulatory obligations. For lenders handling thousands of applications, getting these notices right is as important as making the decisions themselves.
What Is an Adverse Action Notice?
An adverse action notice is a formal notification. The lender sends the notice whenever it rejects a credit application. Several Federal Laws, including the Equal Credit Opportunity Act (ECOA) and the Fair Credit Reporting Act (FCRA), govern these notices. And the reason? Consumers have the right to know why an application was rejected. The law sets specific disclosure requirements. For example, under Regulation B, the notice must identify the credit. The notice should also include an anti-discrimination statement and a valid reason for the decision. However, additional rules may also apply. Adverse action is more than a rejection letter. It allows consumers to have the reason in front of them and, if needed, they could challenge the decision.
Adverse Action Notice Requirements Under U.S. Lending Laws
U.S. lenders must follow two federal laws when issuing adverse action notices. Both laws are directed to protect credit applicants. However, it is important to understand where each law applies.
Equal Credit Opportunity Act (ECOA) and Regulation B
The ECOA prohibits discrimination in credit transactions. Regulation B, however, establishes notification requirements for credit decisions. When it comes to consumer credit, lenders usually have 30 days to notify the applicant of the decision they made.
For consumer credit, lenders generally have 30 days after receiving a completed application to notify applicants of their decision. Different deadlines apply to incomplete applications, counteroffers, and existing accounts.
When adverse action occurs, the written notice must provide specific principal reasons. General references to internal lending policies are insufficient. Certain exceptions and modified requirements apply, particularly to business credit.
Fair Credit Reporting Act (FCRA)
The FCRA imposes additional obligations. When a lender takes adverse action notice based on a consumer report, the FCRA imposes these obligations. The notice must identify the consumer reporting agency. It may include contact information and a clarification that the agency did not make the decision. For borrowers, they can also obtain a free report within a 60-day period of 60 days. Credit score disclosures are required when applicable.
What Information Must an Adverse Action Notice Include?
First things first, the adverse action notice must be clear in its purpose. The information provided must be accurate. The decision made should include the disclosures. As per ECOA, Regulation B, FCRA must deal with the following:
Creditor Information: The name and address of the creditor responsible for the decision.
Adverse Action Taken: A clear statement describing the unfavorable credit decision.
Reasons for the Decision: Specific principal reasons for adverse action or, where permitted, instructions for requesting them.
ECOA Disclosures: The required nondiscrimination notice and contact information for the appropriate federal enforcement agency.
FCRA Disclosures: When a consumer report contributed to the decision, the reporting agency's contact details and the applicant's rights to obtain and dispute the report.
Credit Score Information: The score, related details, and required disclosures when applicable.
Accuracy matters as much as completeness. A generic explanation such as "failed internal lending criteria" may not adequately identify the actual reasons behind a credit denial.
When Must Lenders Send an Adverse Action Notice?
Lenders must issue adverse action notices when certain credit decisions meet regulatory criteria. Common situations include the following.
Loan Application Denial
A lender is obliged to notify the applicant about whatever decision it has made within 30 days of receiving the application.
Credit Limit Increase Rejection
Refusing a borrower's request to increase an existing credit limit can also trigger adverse action requirements.
Unfavorable Changes to Credit Terms
Reducing a credit limit or making certain unfavorable account changes may require notification, subject to regulatory exceptions.
Counteroffers and Modified Terms
When a lender offers different credit terms, and the applicant neither accepts nor uses the credit, adverse action notification requirements may apply.
Adverse action notice criteria still apply even if the borrower hasn’t accepted or used the credit. It is worth mentioning here that not every undesired decision follows the same rules. Several factors, including incomplete applications and counteroffers, have distinct requirements. Lenders must identify the correct trigger before preparing a notice.
How Adverse Action Notices Fit Into Automated Loan Decisioning
Since compliance is at the root, adverse action compliance notification software helps lenders process applications faster. But that does not imply that credit decisions carry no regulatory requirements. So the real responsibility lies with the lender. Because when the decision engine declines an application, lenders still have to assess whether adverse action notice is applicable or not.
1. Application Review
Borrower information enters the underwriting system, along with the financial and identity data needed for evaluation.
2. Risk Evaluation
The Loan Decision Engine assesses the application against configured lending criteria, credit data, and risk parameters.
3. Decision Outcome
After evaluation, the engine returns an approval or decline for further review.
4. Reason Identification
For qualifying adverse actions, lenders identify the specific principal reasons that influenced the decision.
5. Notice Preparation
Required disclosures and decision reasons are assembled into an adverse action notice.
6. Delivery and Recordkeeping
The lender sends the notice through a legally permitted channel and retains the required records.
An automated decline alone does not establish compliance. Lenders must explain the actual reasons behind the decision, regardless of how sophisticated their underwriting technology becomes.
Common Adverse Action Compliance Challenges for Lenders
Loan volume is bound to increase. And when that happens, lenders automate the underwriting process. And that is exactly where adverse action notice becomes complicated. The engine may decline many applicants because the criteria did not match their information. And as lenders cannot review every application manually for adverse action notice, small gaps in decisioning and notification workflows can create larger operational problems.
Inaccurate or Vague Decline Reasons
A decision code may explain why the system rejected an application without identifying the actual principal reasons. Such explanations can leave lenders exposed to compliance violations.
Disconnected Lending Systems
When decisioning engines, loan management software, and notification tools operate separately, information can get lost between systems. Missing or mismatched data makes accurate notice preparation difficult.
Manual Notice Preparation
Preparing notices manually takes time and leaves room for human error. As application volumes grow, lenders face greater risks of incorrect disclosures and missed deadlines.
Incomplete Documentation
Missing decision records or evidence of notice delivery can create problems during compliance reviews. Without reliable documentation, lenders may struggle to demonstrate that they met their regulatory obligations.
How Adverse Action Compliance Notification Software Helps
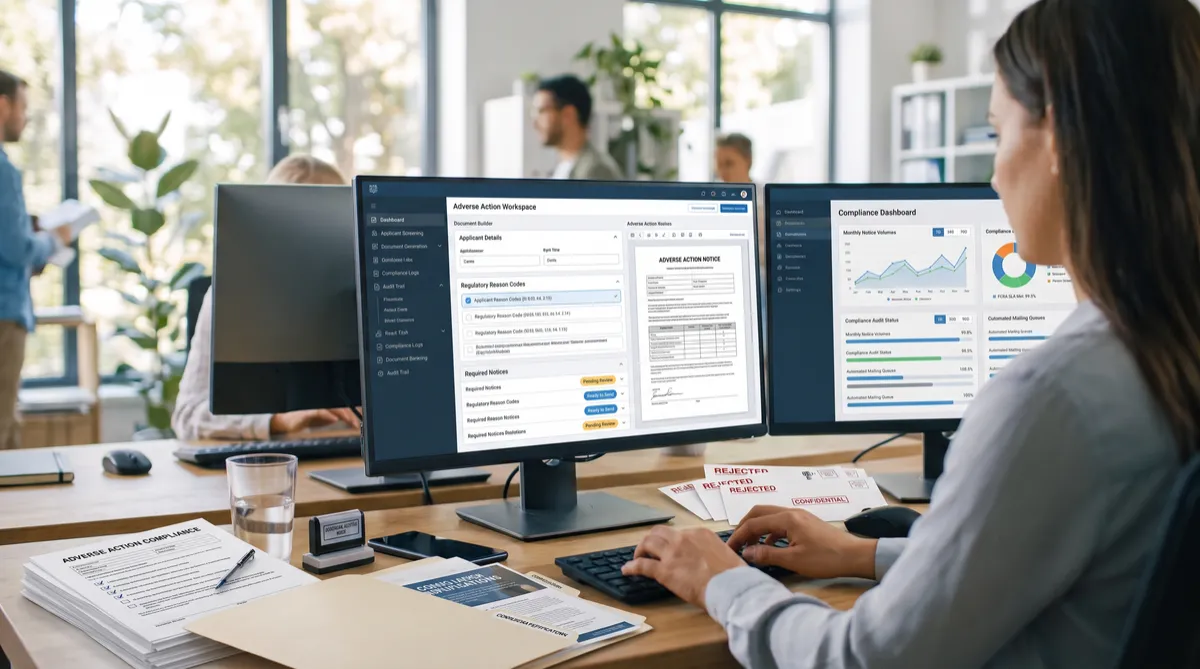
Handling adverse action notices manually becomes difficult as application volumes increase. Adverse action compliance notification software helps lenders manage the process by connecting credit decisions with notice preparation, delivery, and recordkeeping.
Accurate Reason Mapping
The software can map decision outcomes to predefined notice reasons, helping lenders maintain consistency between underwriting results and applicant communications.
Automated Notice Preparation
Configurable templates help generate notices with relevant decision reasons and required regulatory disclosures, reducing repetitive administrative work.
Timely Delivery and Tracking
Automated workflows support notice delivery within applicable deadlines. Tracking features give compliance teams visibility into notification status and potential delays.
Centralized Records and Integrations
Connections with a loan decision engine software and other lending systems help maintain consistent information across workflows. Stored notices and decision records also support compliance reviews and audits.
These capabilities can reduce manual effort and improve operational control. However, lenders remain responsible for ensuring their policies, decision reasons, and notices meet applicable legal requirements.
How Tekambi's NOAAQ Supports Adverse Action Workflows
A credit decline may take seconds. But communicating that decision requires care. Tekambi's NOAAQ is designed to support adverse action notification workflows. With its scrutinized development, the software helps lenders manage compliance.
By bringing notice preparation into the lending process, NOAAQ aims to reduce the manual effort involved in communicating decisions to applicants. For lenders handling large application volumes, a more structured notification process can improve consistency and reduce administrative pressure.
The underlying responsibility, however, remains with the lender. Decision reasons must accurately reflect the credit evaluation, and notices must satisfy applicable regulatory requirements. NOAAQ supports this process without replacing the lender's compliance oversight.
NOAAQ supports automated notice generation, delivery tracking, customizable templates, and timestamped audit records. Tekambi specifically positions it for tribal lending entities and online lenders. These capabilities are confirmed on its official NOAAQ product page.
Conclusion
Rejections happen. And declining a loan application is part of lending. But you still need to justify why those rejections happened. And that explanation is a responsibility lenders cannot afford to let go unnoticed. With an adverse action notice, however, lenders ensure their accountability. And given the more automation in underwriting, the need for accurate explanations and reliable notification processes only grows. A sound compliance process requires more than generating a notice. It demands clear decision reasons, timely communication, and proper documentation. With solutions like Tekambi's NOAAQ, lenders can bring greater consistency to adverse action workflows without adding unnecessary administrative work.




 <